Your Property Tax Bill Is on the Ballot Next Tuesday. Here's the Part Nobody's Talking About
The Local Pulse blog · Dean Kwiatkoski, Realtor
Picture a kitchen island in Delray Beach on a Tuesday morning. The coffee is too hot to drink. Beside it sits last November's property tax bill, pinned under a pepper grinder, with one number circled in pen. Out front, a VOTE NOV 3 sign leans in the grass. The couple at the island are doing the math every Florida homeowner is about to do: if Amendment 3 passes, how much comes off that circled number, and when do they actually feel it?
The headlines have a ready answer, and it comes with a big number attached. It is not the whole answer. On Tuesday, November 3, Florida voters decide whether to rewrite the rules on the biggest bill most homeowners pay all year, and the fine print decides who gets the big number, who has to wait, and why your mortgage payment may not move when you expect it to. If you own in Broward, Palm Beach or Miami-Dade, that fine print is the story.
It's the kind of math Dean Kwiatkoski, Local Expert, knows from both sides of the table. With 20-plus years in South Florida real estate, including 11 years as a mortgage lender, he reads a property tax bill the way a lender does: as part of the monthly payment. Mr. Kwiatkoski is quick to say he isn't telling anyone how to vote. “My job is to make sure you understand what's on the ballot,” he says, “because a lot of homeowners are about to decide on a headline.”
Short answer
Amendment 3 would raise Florida's non-school homestead exemption from $50,000 to $150,000 in 2027 and $250,000 in 2028, if 60% of voters approve it on November 3. Broward's property appraiser estimates average savings near $1,300 the first year. Your mortgage payment may trail the lower tax bill until your lender's next escrow review.
What Amendment 3 actually changes
This is Amendment 3 on your ballot, and it needs 60% of the vote to pass. If it does, most of it takes effect January 1, 2027. Here's the short version, based on the amendment's official summaries and Florida Realtors' reporting:
- Bigger homestead exemption. The part of your home's value shielded from non-school property taxes would rise from today's $50,000 to $150,000 in 2027 and $250,000 in 2028, then adjust with inflation starting in 2029.
- School taxes are excluded. The extra exemption doesn't apply to school district taxes. You'll still get a school tax bill.
- Save Our Homes stays. The cap on how fast your assessed value can rise (the lesser of 3% or inflation) is unchanged, and so is portability.
- Second homes and investment properties. The yearly cap on assessment increases for non-homestead property drops from 10% to 5%.
- New residents wait. People who establish permanent Florida residency after January 1, 2027 generally keep a $50,000 exemption for five years before the larger one applies. If you are buying this year or know a buyer, that is worth knowing; the official ballot text controls.
What it could mean for your bill
Back to the circled number. Your savings depend on two things: your home's assessed value and your local non-school tax rate. The added exemption is $100,000 more than today's on your 2027 bill and $200,000 more on your 2028 bill. Broward Property Appraiser Marty Kiar has estimated an average savings of about $1,300 in the first year and about $2,300 in the second for Broward homeowners. An average is not your number, so here is how to find yours.
Mr. Kwiatkoski offers a quick way to estimate yours: “Take the added exemption and multiply it by your non-school millage rate, which is printed on your TRIM notice.” As an example only, $100,000 times a 13-mill rate (0.013) is $1,300. Palm Beach and Miami-Dade homeowners can plug their own numbers into their county property appraiser's calculator.
One assumption sits behind that math: that rates don't change. Property tax bills are your assessed value minus exemptions, multiplied by a rate that cities, counties and special districts set. The state's Revenue Estimating Conference projected that cities and counties could lose nearly $12 billion a year by 2031. Supporters see that as relief for families. Critics worry about police, roads and stormwater budgets, and some local governments could raise rates to make up part of the gap. Neither side is making things up. That's the tradeoff.
Where people stand: Governor DeSantis and Senator Rick Scott have said they will vote for it. The Florida Sheriffs Association, the Florida State Fraternal Order of Police and Florida's professional firefighters have raised concerns about public-safety funding. In August, a Leon County judge also ruled that the original ballot summary was misleading and ordered it rewritten, so read the language you will actually see before you vote.
The part nobody's talking about: your mortgage payment
This is where Dean's 11 years on the lending side matter most. “It stops being a credential and starts being useful,” he says.
“Think of escrow as a jar,” Mr. Kwiatkoski explains. “Your lender drops a little in every month, then empties it at the county's door when the bill comes due.” If your taxes are paid through escrow, the first bill with the bigger exemption would arrive in November 2027, but the jar doesn't know that until your lender looks inside. Lenders review escrow accounts at least once a year, and your payment adjusts at that review, so the lower payment can trail the lower bill by months. Homeowners who pay taxes themselves would feel the savings sooner, in one lump.
For buyers it goes the other way, and it's good news. According to Dean Kwiatkoski, lower taxes mean a lower monthly cost of owning, which can help a buyer qualify. Every $1,000 a year in lower taxes is about $83 a month, and at today's 7.32% rate that's roughly $12,000 of additional loan a buyer might carry. “That's the kind of detail that shows up in home values, in negotiations, and in how fast homes sell once a rule like this takes hold,” he notes.
What your neighbors are talking about
For sellers, a lower yearly carrying cost can make a homesteaded property more appealing, because buyers shop by monthly payment. For buyers, the picture is more mixed. A seller's current tax bill is not a safe guide to what you will pay, because Save Our Homes resets when a home sells, and a buyer who becomes a Florida resident after January 1, 2027 may only get the smaller $50,000 exemption for the first five years. Mr. Kwiatkoski's advice is to have your agent and your lender run the payment both ways before you write an offer. With a background bridging both real estate and mortgage lending, Dean sees this from both sides of the balance sheet, and he points to an escrow estimate built on the seller's old bill as a known trap.
What to do this week, whichever way you vote
Dean's short list for homeowners, whichever way the vote goes:
- Confirm your homestead exemption is on file. If you moved or bought recently and never filed, you're not getting the current benefit, let alone a bigger one. Filing is done with your county property appraiser, and the deadline is March 1.
- Know your current numbers. Pull your last tax bill and note your assessed value, your exemptions and your non-school rate. That's what you'll compare against in 2027.
- Ask your lender about escrow timing so you aren't surprised either way.
- Don't change your plans on an assumption. If you're thinking about selling, buying or refinancing, the numbers are worth running both ways.
Back at that kitchen island, the number is still circled in pen. “Whatever Florida decides on November 3,” says Mr. Kwiatkoski, “the homeowners who already know their assessed value, their exemptions and their non-school rate are the ones who won't be guessing in 2027.”
Frequently asked questions
When would I see a property tax cut if the amendment passes?
The new exemption would take effect January 1, 2027, so it would first appear on your tax notice in August 2027 and your bill in November 2027.
Does the larger homestead exemption apply to school taxes?
No. The added exemption applies only to non-school taxes. The existing $25,000 school exemption stays as it is.
Will my mortgage payment go down if my property taxes drop?
Only if your taxes are escrowed, and only after your lender's next annual escrow review. The lower bill and the lower payment usually don't arrive on the same day.
Does this change Save Our Homes or portability?
No. The assessment cap and portability stay the same.
What if I pay my property taxes myself, without escrow?
You would feel the savings when you pay the lower bill, which would first arrive in November 2027.
The TL;DR: Amendment 3 would raise Florida's non-school homestead exemption to $150,000 in 2027 and $250,000 in 2028 if 60% of voters say yes on November 3. The first lower bill would arrive in November 2027, and a lower mortgage payment can trail it until your lender's next escrow review.
Dean's “Lender's Eye” perspective: A tax cut only helps your monthly budget once it reaches your escrow account, so know your escrow review date and your current assessed value now.
Recommended next step: Pull your last tax bill, confirm your homestead exemption is on file, and ask Dean for a quick estimate of your 2027 and 2028 numbers at deansellsfl.com.
Dean can walk you through the numbers for your specific property: how this could affect your 2027 and 2028 bills, plus what your home is worth in today's market. Start at deansellsfl.com for a free valuation, or call or text 561-948-3480.
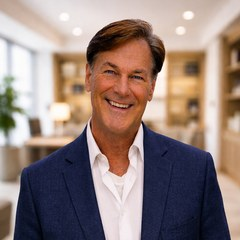
Over two decades of experience in the real estate industry. His strong background in finance and loan origination, coupled with exceptional negotiation skills, sets him apart. While other Realtors may accept an offer or price that is less than ideal, Dean accomplishes results that surpass his clients' expectations.
Dean Kwiatkoski | Realtor | Signature International Real Estate | 561-948-3480 | [email protected] | www.DeanSellsFL.com
Sources: Florida Legislature CS/HJR 1F and JMCO summary of the amendment; Florida Realtors; Pinellas County Property Appraiser Amendment 3 FAQ (pcpao.gov/amendment3); NBC 6 South Florida (Broward Property Appraiser estimate); WFTV (exemption phase-in and new-resident rule); CPA Practice Advisor, July 2026 (Revenue Estimating Conference estimate); WPTV and News4Jax, August 2026 (opposition, support and the court ruling on ballot wording). This is general information, not tax or legal advice; ask your property appraiser or tax professional about your situation.
Call/Text 561-948-3480 | [email protected] | www.DeanSellsFL.com
EXPERIENCE | KNOWLEDGE | RESULTS
